

France’s rising debt costs are adding pressure to public finances already strained by high borrowing and political uncertainty. The premium investors demand to hold French bonds over German debt reached 177.7 basis points on October 22, its highest level since November 2011, according to Reuters.
The spread reflects the extra return investors seek for lending to France rather than Germany. Economists cited by DW said concerns include the country’s debt burden, budget deficits and political instability. France’s public debt is around 120% of gross domestic product, the report said.
Higher borrowing rates can increase the cost of refinancing existing bonds and of issuing new debt to cover government spending. France is expected to pay more than €79 billion in interest on total public debt in 2026, rising to more than €91 billion in 2027, DW reported. Those estimates include social security funds and local authorities; the central government’s interest bill is estimated at €62.6 billion.
Protests and political pressure
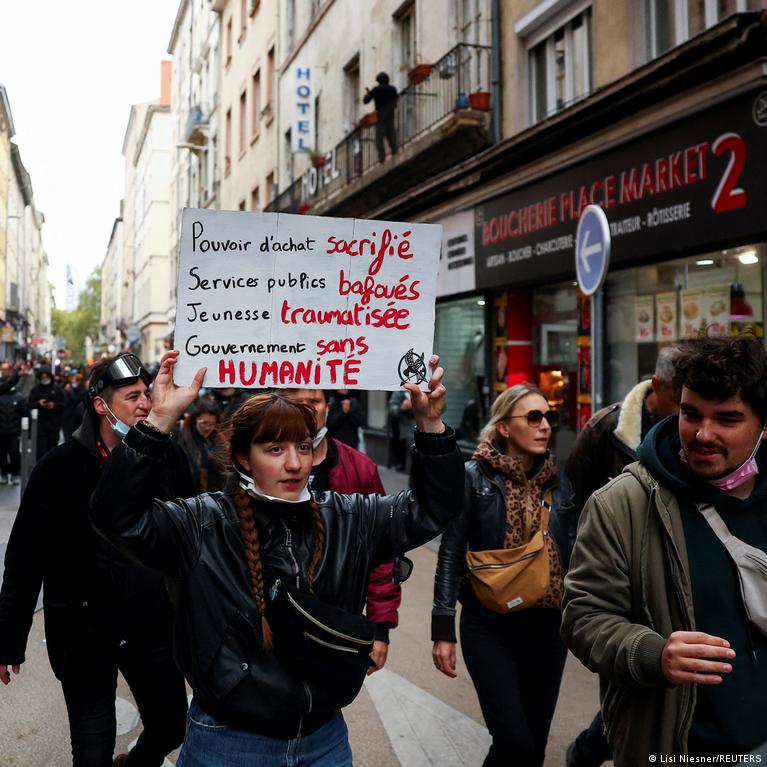
Large demonstrations were reported across France on November 5, with protesters demanding higher wages and supporting student demands, according to the Associated Press. The protests add to the political strain facing a government without a parliamentary majority, as parties on both the far right and far left promote costly policy proposals.
ZEW economist Friedrich Heinemann told DW that a sharp rise in the bond spread could tighten financing conditions beyond the state, including for borrowers in France. Landry Charrier, a researcher at the University of Bonn, said many people may not feel the consequences of public debt directly in daily life, limiting pressure for change.
France last balanced its national budget in 1974, according to DW. The higher interest bill leaves less room in future budgets for other spending as the state continues to refinance debt and fund deficits.
 Reid Bentley